Condominium accounting in Morocco: what decree 2.23.700 requires
A decree published in the official bulletin requires standardised accounting from condominium managers, with obligations that increase according to the level of charges managed.
What the text requires
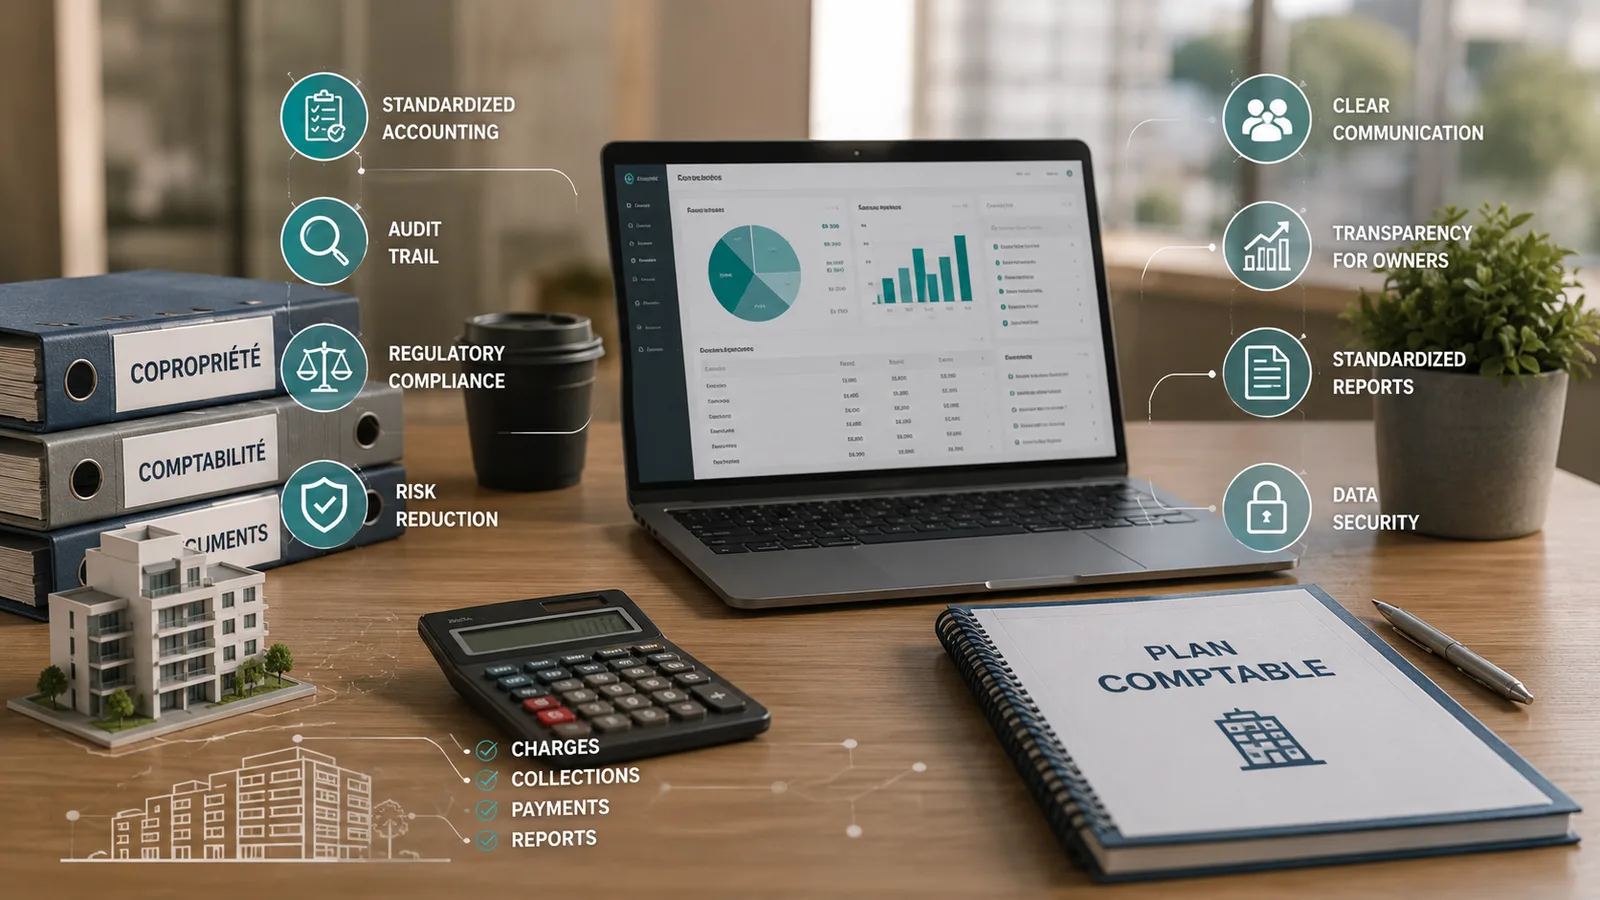
Decree n° 2.23.700 of 22 rajab 1446 (23 January 2025), published in Bulletin Officiel n° 7391 of 31 March 2025 under law 18.00 on the status of co-ownership of built property, governs condominium-manager accounting. It requires standardised bookkeeping, with requirements intensifying as the amount of charges called rises — above a certain threshold, an audit of the accounts becomes necessary.
Two points that come up every time. There is no minimum number of units: every copropriété is covered, whatever its size. And the three-tier classification is based on the charges called (invoiced) over the financial year — not on the number of units, and not on the amounts actually collected.
The obligations apply from the first financial year opened after publication of the decree. For a copropriété whose year follows the calendar, that means the year opening on 1 January 2026. Non-compliance exposes the manager, including their mandate.
Why spreadsheets no longer suffice
An Excel file can produce a balance. It does not produce standardised accounting, keeps no audit trail, and does not survive a line-by-line request for justification. The problem is not the manager's competence: the tool was never designed for this.
What a tool needs to do
- Charge calls per unit, with the apportionment key applied and traceable.
- Tracking of receipts and arrears, including reminders.
- Accounting conforming to the required chart, with the expected statements.
- A consultable history: who entered what, when, and against which document.
- Communication to owners — because accounting that is correct but unreadable does not settle the dispute.
Who is covered, and who is not
Every copropriété governed by law 18.00, with no exemption for size. There is no minimum number of units: a residence of eight apartments falls under the same text as a complex of three hundred. What varies with size is not whether the decree applies — it is the level of obligation.
The accounting duty falls on the syndic, whether professional or a volunteer. That is the point volunteer-managed buildings discover last: the text provides no lighter regime because nobody is being paid. The conseil syndical oversees; it does not keep the books in the syndic's place.
Outside the scope: buildings that are not held in co-ownership under law 18.00. A block owned by a single landlord and let out is accounted for by that owner, not by a syndicate of co-owners.
The documents a manager must now produce
- A forecast budget for each financial year, put to the general assembly.
- A management account for the year just ended, setting the forecast against the actual.
- Year-end financial statements drawn up on the standardised chart of accounts — not in an in-house format.
- The accounting books: journal, general ledger, and every entry attached to a unit, an owner and a financial year.
- Supporting documents retained and retrievable, invoice by invoice. A balance without documents is not accounting.
Three levels of obligation, by charges invoiced
The text grades requirements into three levels, determined by annual charges invoiced — not by the number of units, and not by the amounts actually collected. The thresholds sit around 200,000 MAD and 500,000 MAD.
The heaviest practical consequence is at the top level: above the upper threshold, an audit of the accounts becomes necessary. That changes the shape of the financial year, because you have to produce auditable accounts by a date rather than presentable accounts on assembly day.
Note what "invoiced" means. A copropriété that calls 520,000 MAD in charges and recovers only 380,000 MAD is classified on the 520,000. A poor collection rate does not move you down a level — it only makes the level harder to meet.
What compliant accounting actually looks like
In practice, four things have to be true at once:
- Every charge call is attached to a unit, with the apportionment key applied and visible.
- Every receipt is attached to the call it settles — not merely to the owner's account.
- Every entry carries its document, and the history says who entered what and when.
- Year-end statements are produced by printing them, not by reconstructing them.
That last point is the simplest test. If producing the assembly accounts takes a week of work and an intermediate spreadsheet, the books are not being kept — they are being rebuilt once a year.
What a manager risks by not complying
The text does not need to set a fine to bind. A failure engages the syndic's responsibility in carrying out the mandate: the general assembly can demand an account, refuse discharge, and revoke the appointment; and management whose accounts cannot be justified is exposed to a civil liability claim.
For a professional syndic the risk is commercial before it is legal. A copropriété that discovers its accounts are not produced in the required form changes supplier at the next assembly.
A worked example, on a small building
Take a residence of 24 units, 180,000 MAD of charges called for the year, volunteer-managed. It is covered — no unit threshold excludes it — and it sits below the first threshold, so at the lightest level of obligation. What it must still produce: an approved forecast budget, a management account, statements on the standardised chart, and retrievable documents.
What that changes for them in practice: the volunteer treasurer's spreadsheet can stay as the starting point, but it produces neither the statements in the expected format nor the audit trail. The cost of compliance is not a 100,000 MAD system — it is a tool that holds the chart of accounts and the history. Conversely, the same residence moving to 540,000 MAD of charges called after major works are voted would cross the upper threshold and have to have its accounts audited. That is the case where compliance has to be planned a year ahead rather than discovered at the assembly.
A market already served — and what that means for you
Several property-management packages exist in Morocco, some free, often priced per unit per month. If your need is accounting alone, one of them will probably do, and we will tell you so.
Custom development is justified in a different case: when you manage a large portfolio, need an integrated resident portal and field application, or when management sits alongside a property-development business. That is what we built with Residapp — 15 residences, 2,000 units, complaint-handling time down 70 %.
Related articles
Compliance & regulation
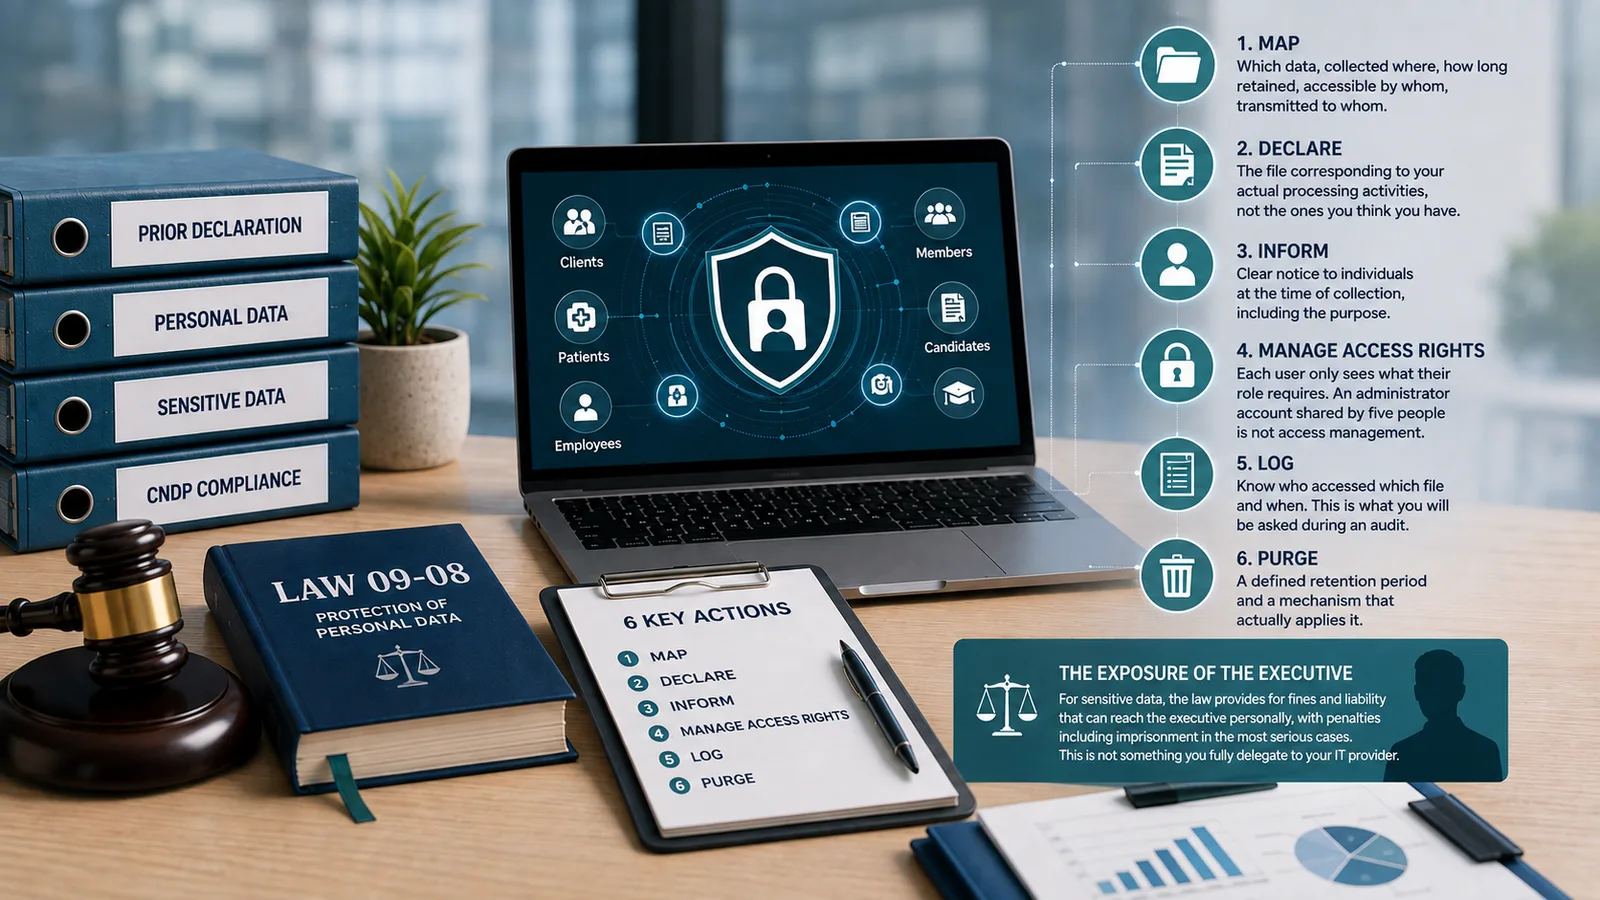
CNDP compliance: what a Moroccan company actually has to do
Morocco's data-protection authority has stepped up enforcement and explicitly names healthcare, pharmaceuticals, hospitality, e-commerce and higher education. Here are the concrete obligations — and the director's personal exposure.
Compliance & regulation
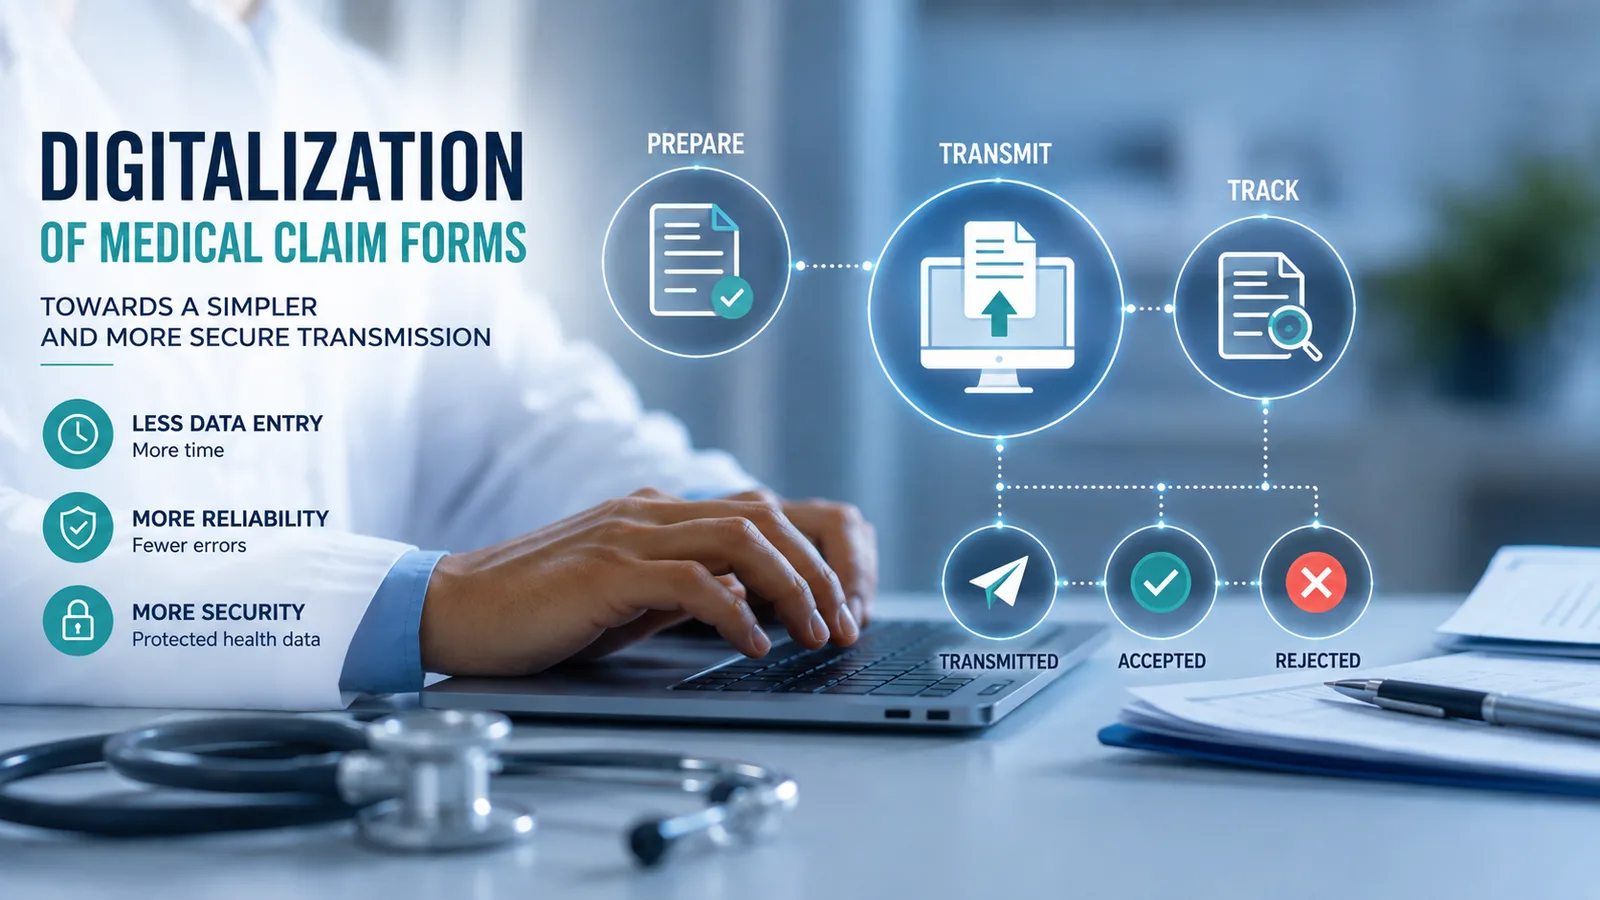
CNSS electronic care claims: what changes for clinics and laboratories in Morocco
Electronic submission is becoming the norm for doctors, pharmacists and laboratories. The important detail: it can happen through the insurer's portal, or through your own software.
Compliance & regulation
Getting a digitalisation project co-funded: how it actually works
Several Moroccan public schemes co-fund digital transformation for small and medium companies. Here is the mechanism, the usual conditions, and the mistakes that waste a cycle.
Newsletter
Get our upcoming articles straight to your inbox.